
Health insurance is complicated.
Dave makes it understandable.
Understand what coverage matters for your situation, learn how your options differ, and make a more informed decision—with an expert there when you need one.
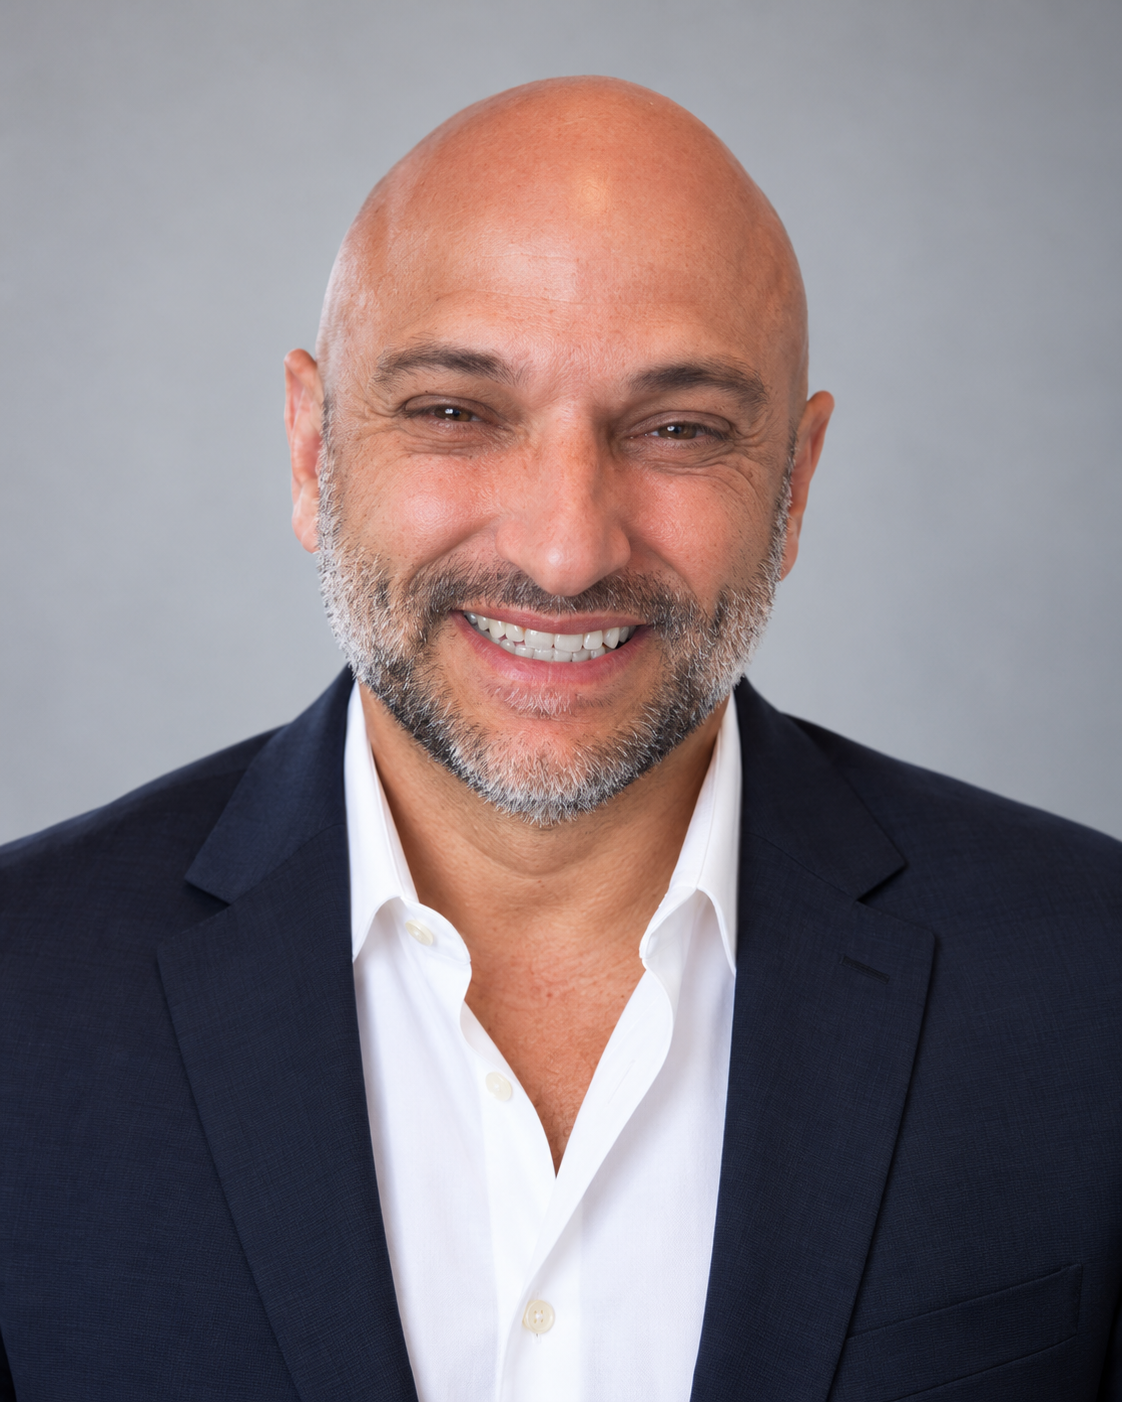
"I don't sell plans off a spreadsheet. We map your doctors, your real budget, and your actual risk first."
— Dave Gagleard, Licensed Health Insurance BrokerMost insurance sites start with products.
Dave starts with you.
The traditional insurance market dumps 40 confusing plan brochures into your lap and asks you to pick a deductible. Dave reverses the entire experience: understand your healthcare patterns, identify your doctors, define your risk tolerance, and then filter only what fits.
Understand Yourself
Your life stage, household structure, 1099 vs W2 status, and doctor dependencies.
Understand Coverage
Clear translation of deductibles, copays, out-of-pocket maximums, and network boundaries.
Understand Options
Objective comparison between Marketplace, Private PPO, Small Group, and Supplemental paths.
Ask Dave
Review your specific doctors and medications directly with a licensed health insurance broker.
Decide With Confidence
Enroll with total clarity and maintain ongoing support whenever questions arise.
Ready to see where your situation fits?
Take the 3-minute guided Coverage Path. No high-pressure sales calls, no fake quotes.
Before choosing a plan, understand what matters to you.
Health insurance decisions fail when people shop for numbers without examining how those numbers behave in real life.
Your Doctors
Will you have to change your trusted physicians?
In-network directories change constantly. If you see specific specialists or obstetricians, verifying active network contracts is step one before looking at prices.
Your Network Structure
Do you travel or require specialist freedom?
An HMO locks you to county borders with referral gates. A PPO offers nationwide open access without needing primary care permission slips.
Your Prescriptions
Are your daily medications on the plan's formulary?
A plan that saves $50/mo on premium is worthless if your essential tier-3 medication costs $300/mo more out of pocket.
Your Healthcare Usage
Do you visit doctors quarterly or only for annual checkups?
Healthy individuals with rare medical usage benefit dramatically from different deductible designs than families managing chronic physical therapy or asthma.
Your Real Monthly Overhead
Are you factoring premium + copays together?
The cheapest monthly premium frequently carries the highest total cost of care. Dave calculates your realistic annual spend.
Your Catastrophic Risk Exposure
What happens if a major unexpected diagnosis occurs?
Your Out-of-Pocket Maximum is your true financial firewall. Knowing this exact ceiling prevents sudden catastrophic medical bankruptcies.
Dave Knows.
Insurance companies invent complex jargon to obscure what you actually pay. Dave translates the terminology so you can make informed choices.
Monthly Premium vs Total Cost
A lower monthly premium doesn't automatically mean lower healthcare expenses.
PPO vs HMO
HMOs require local primary gatekeepers; PPOs give nationwide direct access.
Deductibles & Copays
Deductible is what you pay first; Copays are flat fees for routine care.
Out-of-Pocket Maximum
The legal financial ceiling protecting you from catastrophic medical debt.
Self-Employed Coverage Strategy
Business owners need flexibility, write-offs, and year-round enrollment freedom.
Special Enrollment vs Year-Round Access
Marketplace plans have strict deadlines; certain private options are open year-round.
All explanations vetted by Dave Gagleard
No automated sales scripts or biased marketing copy. Plain-English truth based on years of daily brokerage experience.
Understanding creates trust.
Trust creates the conversation.
Take the guided Coverage Path to clarify your priorities, or reach out to Dave directly when human expertise is the right next step.